October 6, 2026 · Market Update
Midtown Market Update: September 2026
Midtown went quiet in September, but the pause was not surrender.

The Short Version
Both sides waited at the same door in September. Buyers paused. Sellers held back. The market went quiet, but nobody flinched.
GTA sales came in at 5,040 in September, down 9.0% year over year. Across all home types, the average selling price of $1,006,409 was down 5.1%, and the MLS Home Price Index composite fell 4.7%. Those headline numbers mix freehold houses with condominiums, and condos are doing most of the pulling down.
The deeper story is confidence. Buyers can pay today's prices. They need to believe their jobs will hold and inflation will not push borrowing costs back into the conversation.
Midtown by District
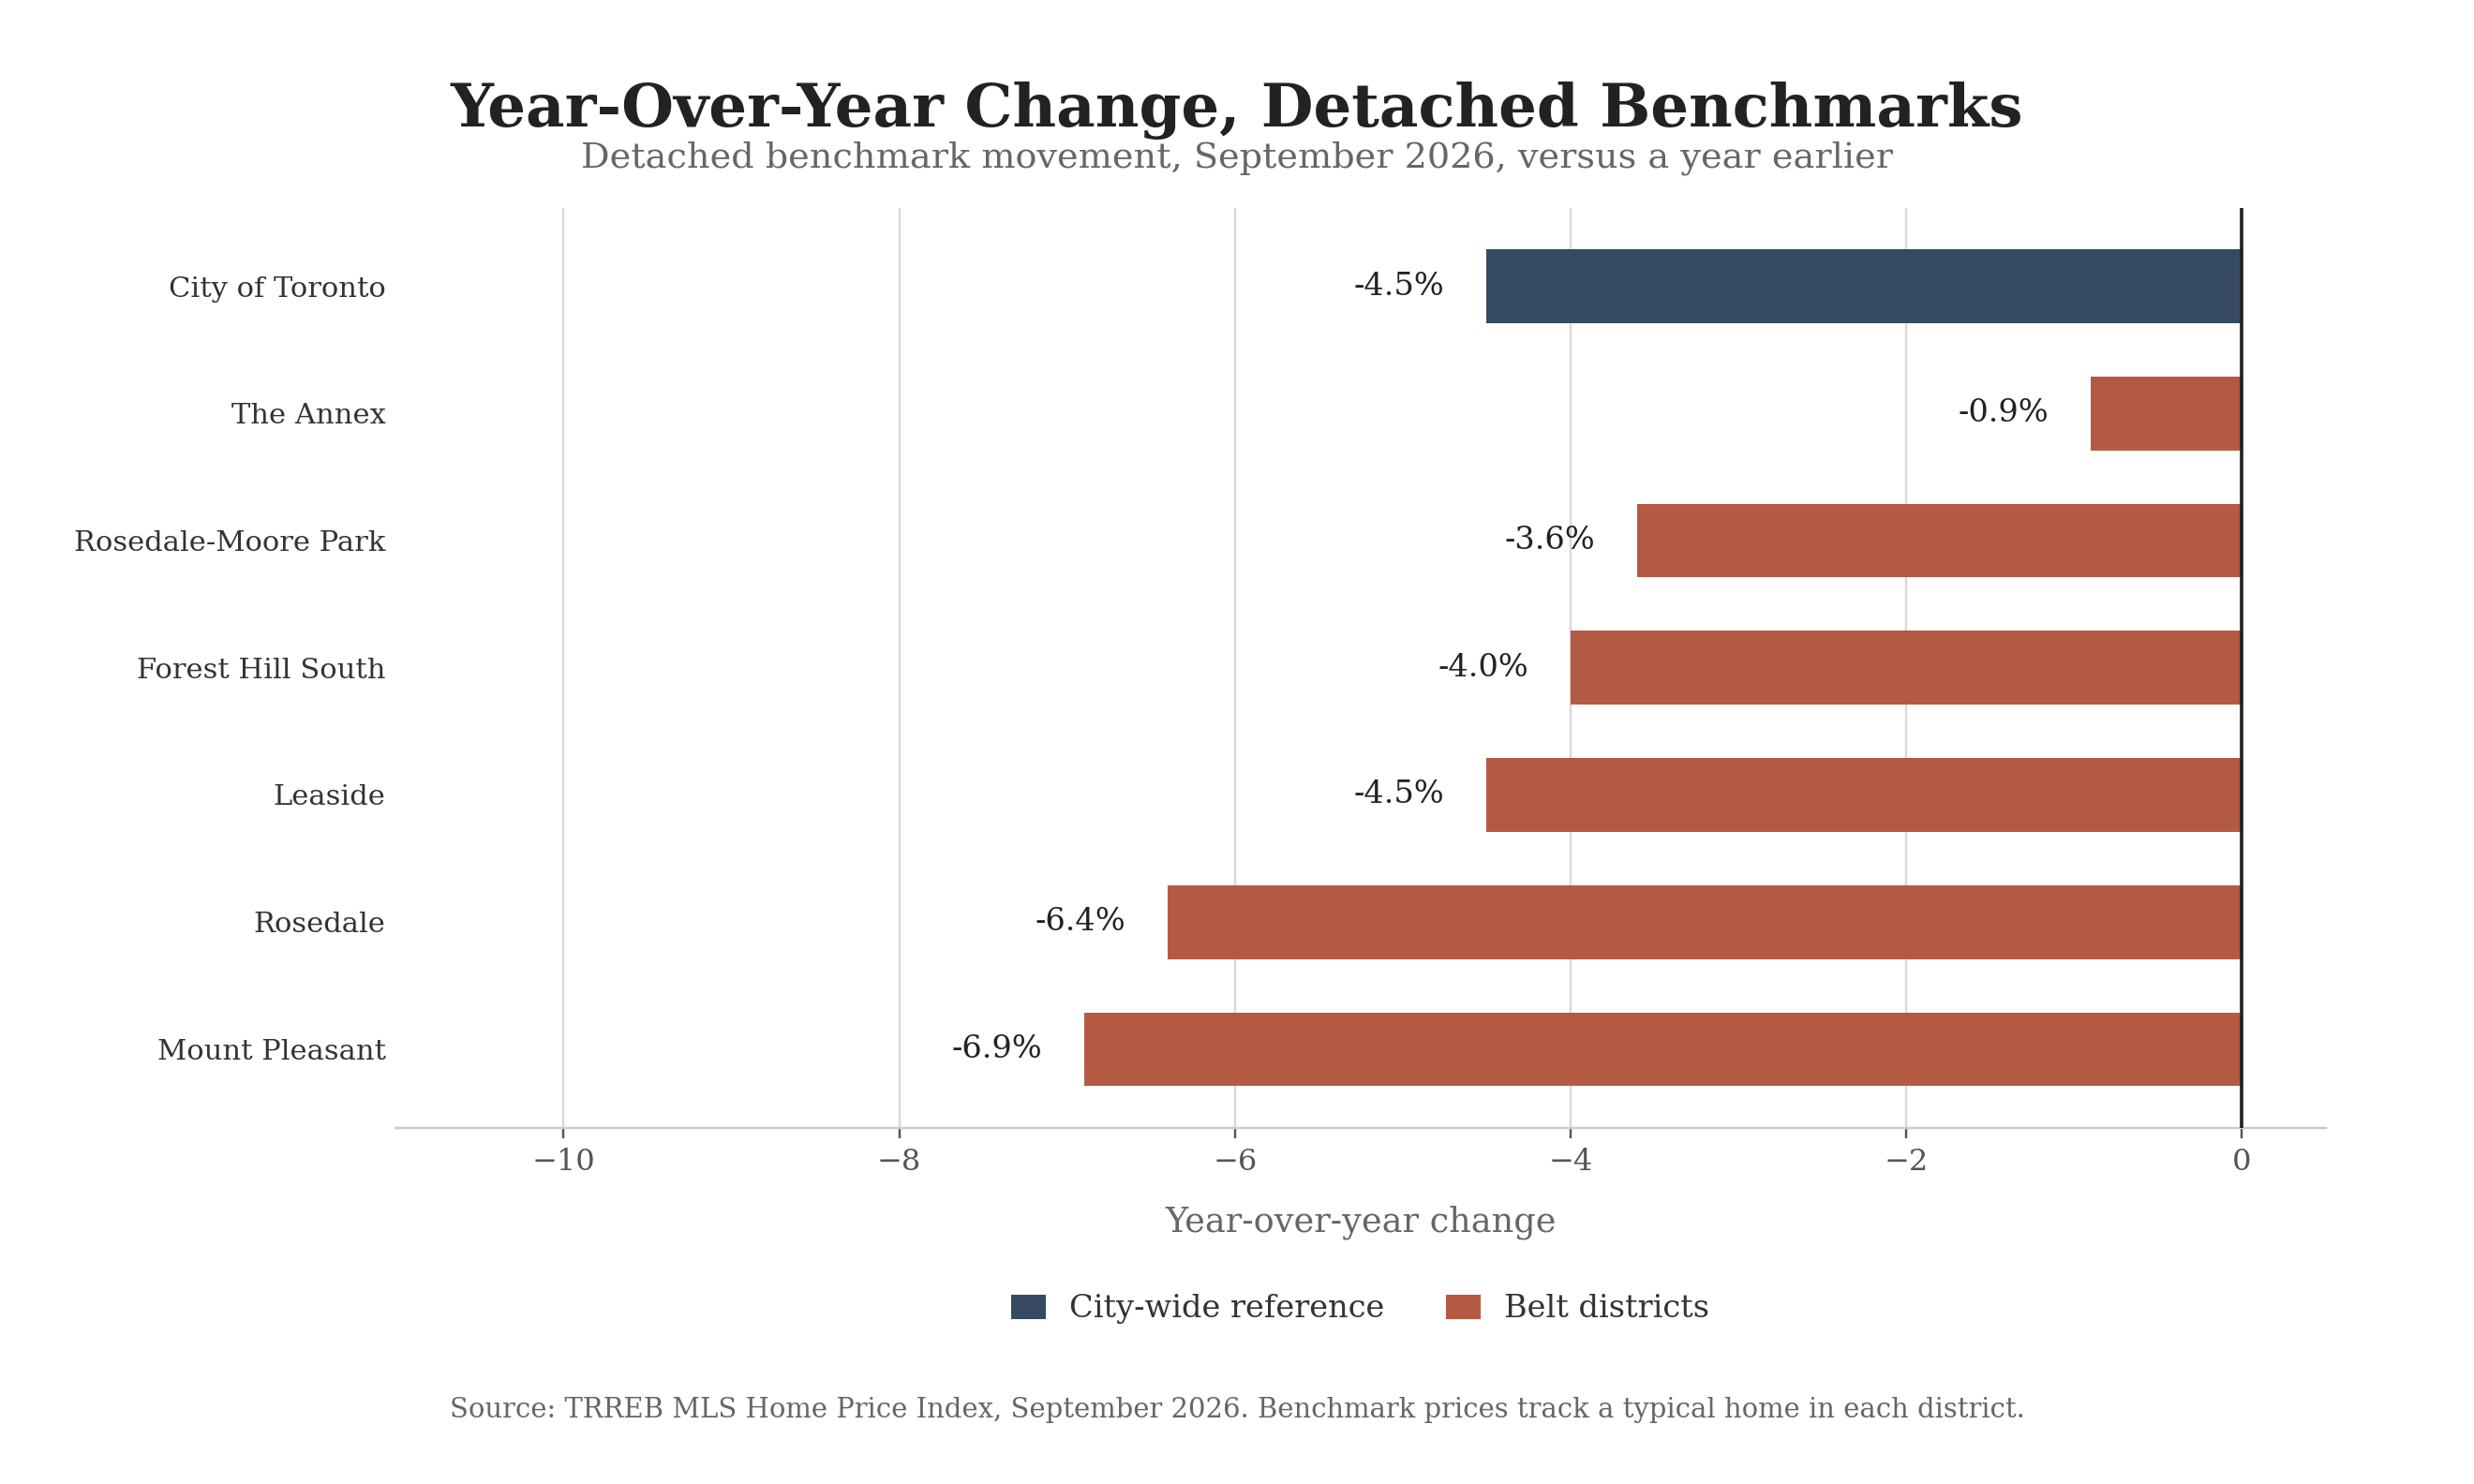
In the City of Toronto, the composite benchmark across all home types sat at $908,200, down 3.8%. The detached benchmark, freehold houses only, sat at $1,417,600, down 4.5%.
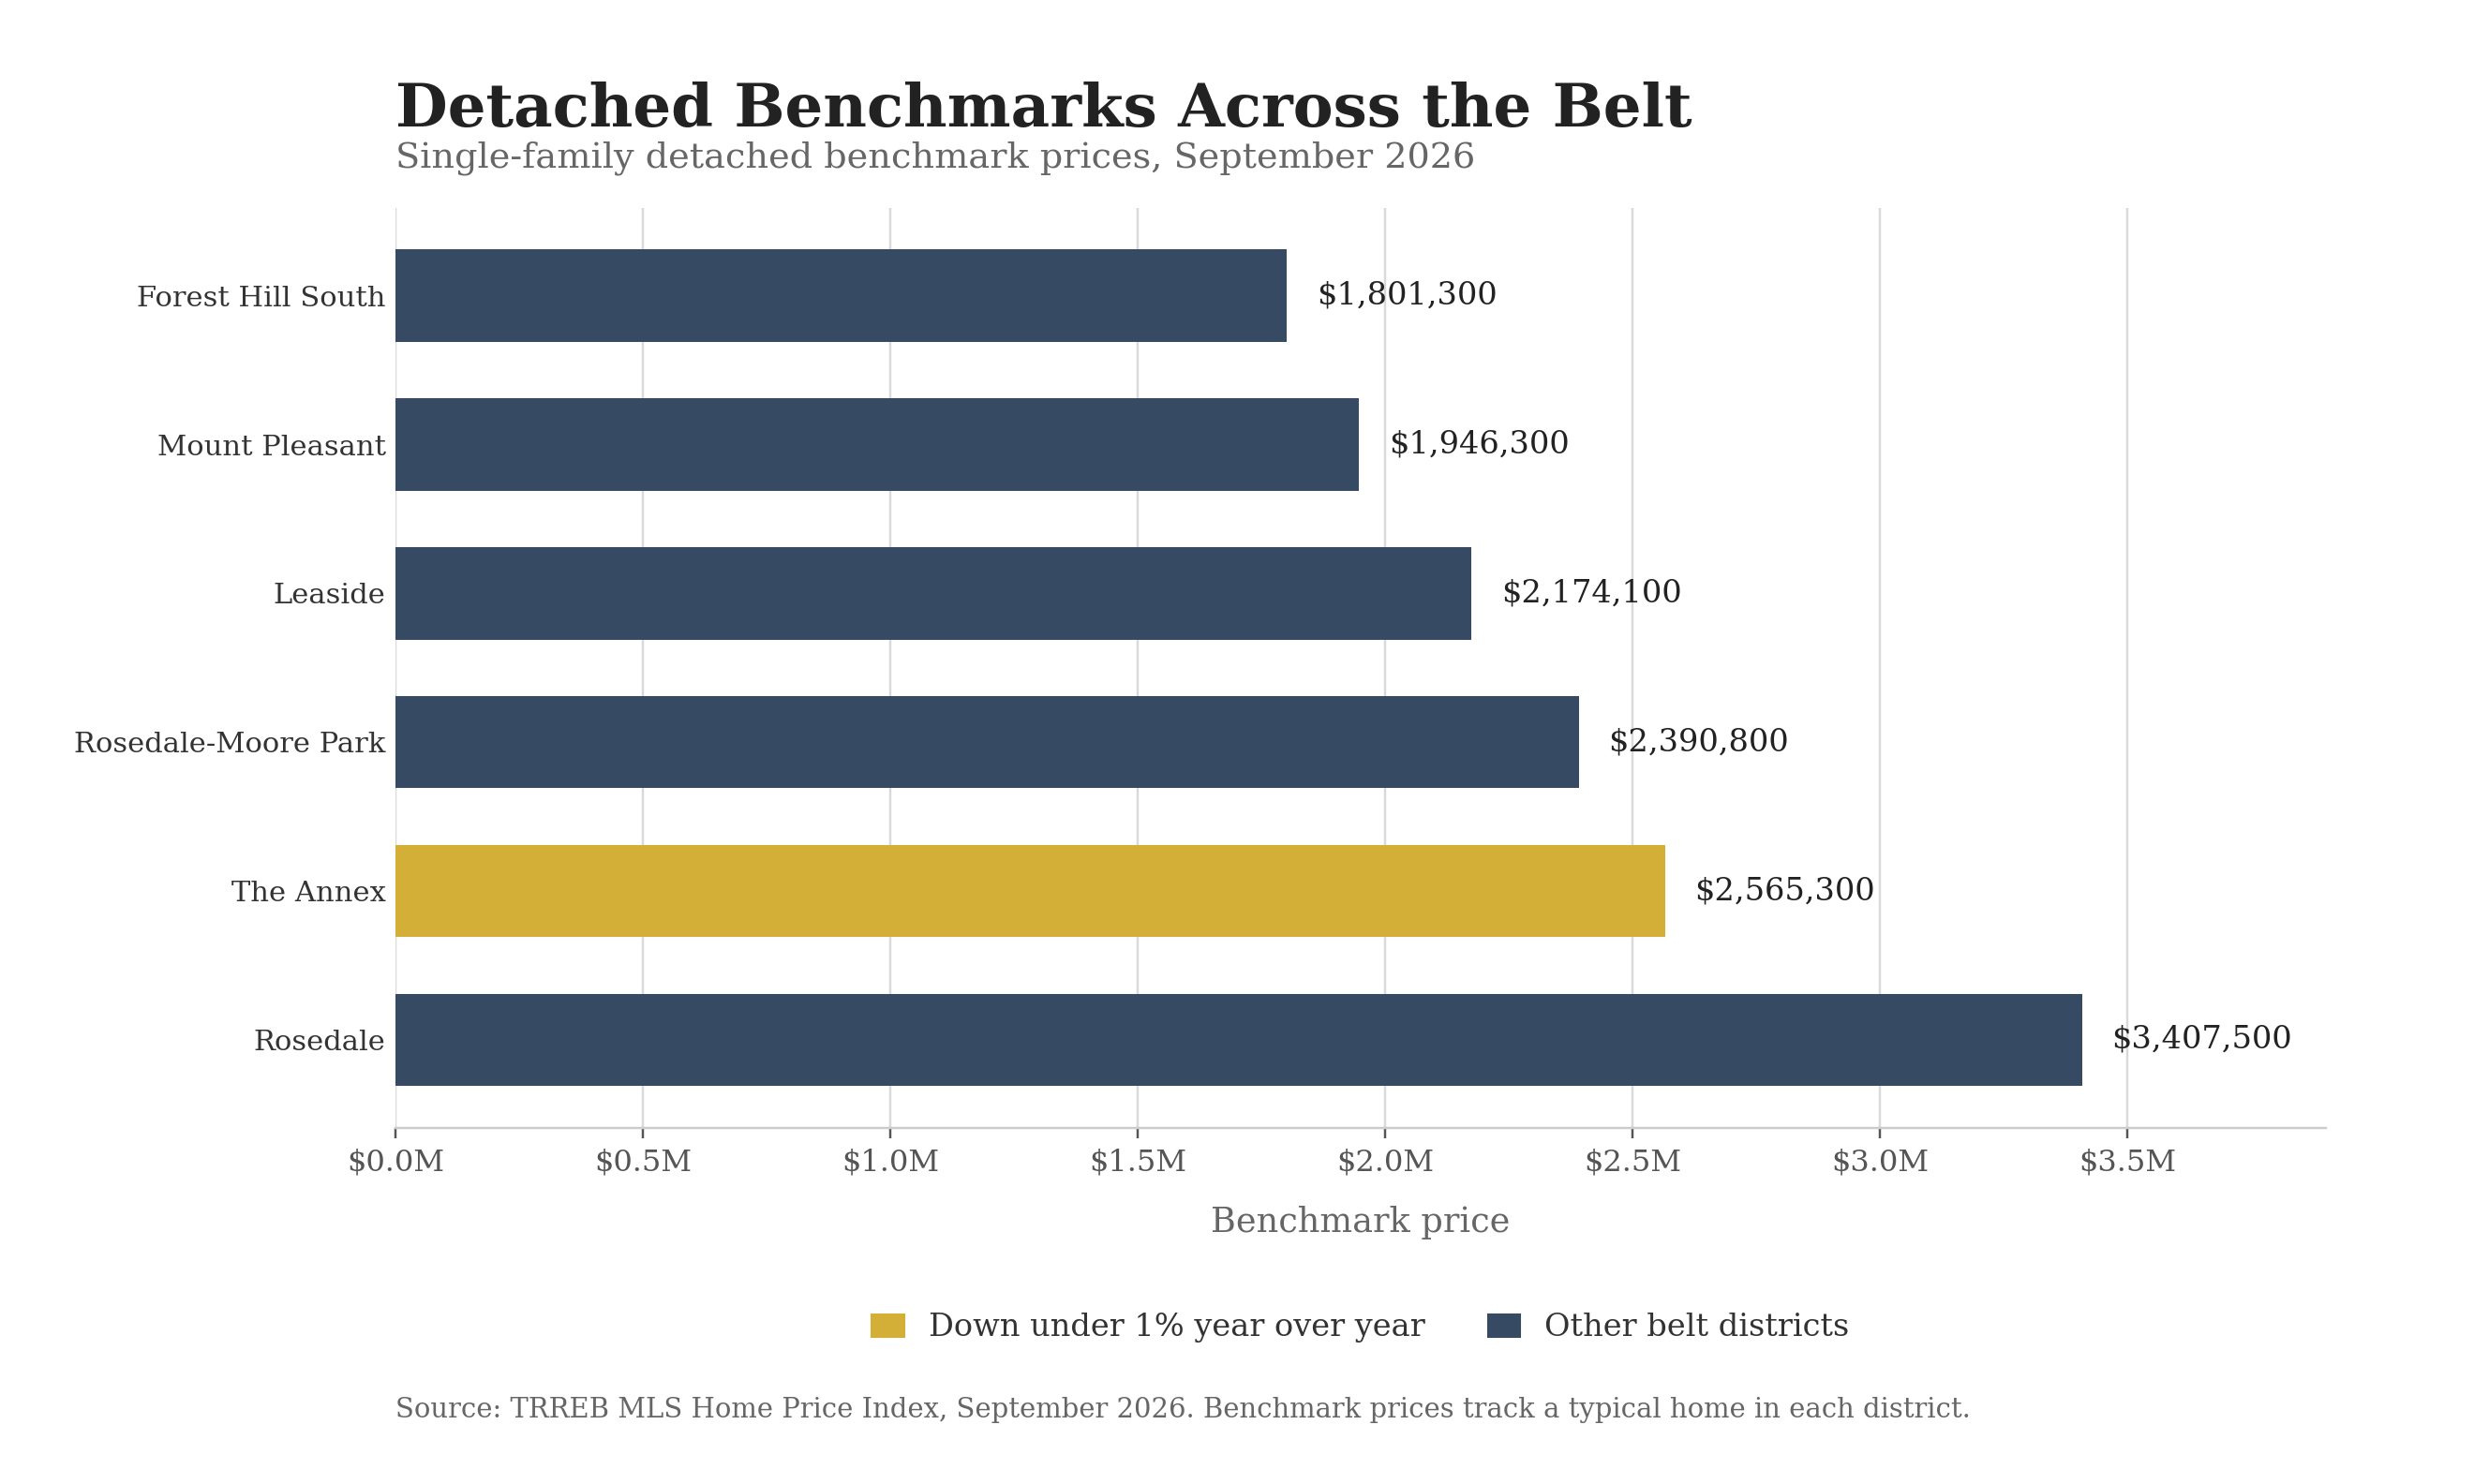
Inside the belt, detached benchmarks year over year:
- Rosedale: $3,407,500, down 6.4%
- The Annex: $2,565,300, down 0.9%
- Rosedale-Moore Park: $2,390,800, down 3.6%
- Leaside: $2,174,100, down 4.5%
- Mount Pleasant: $1,946,300, down 6.9%
- Forest Hill South: $1,801,300, down 4.0%
On the composite measure, no district in the belt posted a gain, but two came close: Mount Pleasant, down 0.8%, and The Annex, down 0.9%, against a city composite down 3.8%. The story this month is steadiness in the middle of the belt. The Annex detached benchmark is down 0.9% in a city where the detached benchmark fell 4.5%.
Rosedale, Leaside and Mount Pleasant each set their detached benchmark on fewer than a dozen sales in September. That matters. Thin sales can make the monthly read look sharper than the real market feels on the ground. Read those single months against the trend, not on their own.
Behind the Numbers
New listings came in at 16,500, down 14.4% from a year earlier, and active listings eased 9.3% to 26,131. Seasonally adjusted new listings fell in September from August.
That is the pressure buyers can miss. The market feels slow because demand eased. But owners also held back, so choice did not open the way some buyers expected. GDP was up 3.3% in the second quarter and labour conditions have improved. Few owners are being forced out.
The belt held while the city eased. Waiting for a broad correction means waiting on districts that are not correcting.
The Bank of Canada held its target for the overnight rate at 2.25% on September 2. Inflation has been hovering around 3%, mostly on gasoline. Excluding gasoline, it was 2.2% in July. The Bank flagged upside risks from energy prices and from new tariffs after Canada-US trade talks broke down.
For Buyers
This is not a market to chase. It is a market to read carefully.
The apartment benchmark was down 6.7% across the GTA, and condominiums remain the softest segment. That is where softness is clearest. In Midtown houses, the better story is selectivity, not collapse.
TRREB Chief Information Officer Jason Mercer points to substantial pent-up demand, with households intending to purchase in the months ahead. People are not gone. They are waiting for confidence.
And the sellers who listed in September were mostly choosing to list. Sellers who list in the fall tend to be sellers who mean it, and the negotiating room is real on the properties that have sat.
For Sellers
Average days on market across all home types came in at 34, up one day from last year. That is not a broken market. It is a market with less room for wishful pricing.
The homes that sit are the ones priced for last year. Fewer buyers are walking through, but the ones still looking tend to be serious. A well-priced house can stand out more clearly in a thin market than in a crowded one.
Price against today's numbers, especially on condominiums, where prices have eased the most. A good house at a defensible number will still trade. The discipline is in the opening number.
What I'm Watching
October 28 is the Bank of Canada's next rate decision, released with the Monetary Policy Report. The September statement said the Bank is prepared to adjust policy as needed. That date matters because this market is trading on confidence as much as affordability.
The fall listing trend matters more for what buyers will see. Seasonally adjusted new listings fell in September from August. October will show whether owners keep waiting or come to market.
TRREB President Daniel Steinfeld called housing one of the biggest issues on voters' minds, with the municipal election set to shape housing policy across the GTA and Simcoe County for the next four years. Policy will stay in the background of every pricing conversation, along with borrowing costs, job security and supply.
Closer to home, I am tracking whether Midtown's steadiest districts keep holding value. The Annex and Mount Pleasant ended September within a point of flat. Next month I will compare that against any change in listings, district by district.
The Bottom Line
September was a holding pattern. Buyers waited for conviction. Sellers waited for proof.
What breaks it is confidence. Not a dramatic discount. Not a flood of listings. Just enough certainty for people to move.
The numbers above are district-level. The right number for any given block is still a conversation. That is where the market is now.
Sources: TRREB Market Watch, September 2026; Bank of Canada.